Published : 16 Nov 2026, 12:23 AM
Updated : 16 Nov 2026, 12:22 AM


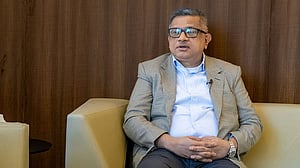
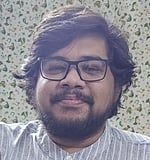
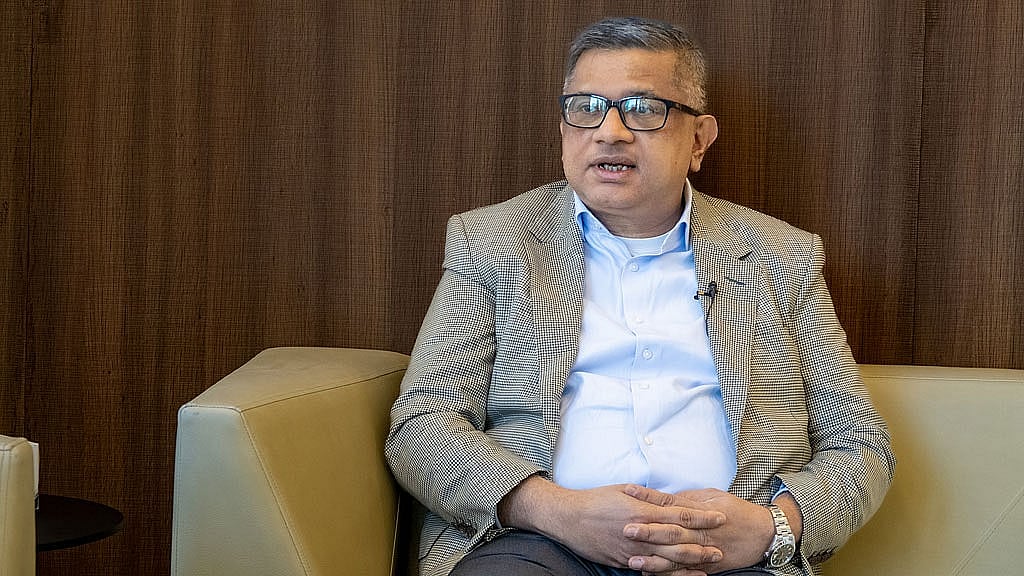
Winning back customers’ trust is the toughest challenge facing Bangladesh’s troubled banking sector, says ONE Bank Chief Executive Officer and Managing Director Muhit Rahman.
He believes confidence in deposits must be restored before lenders can expand credit.
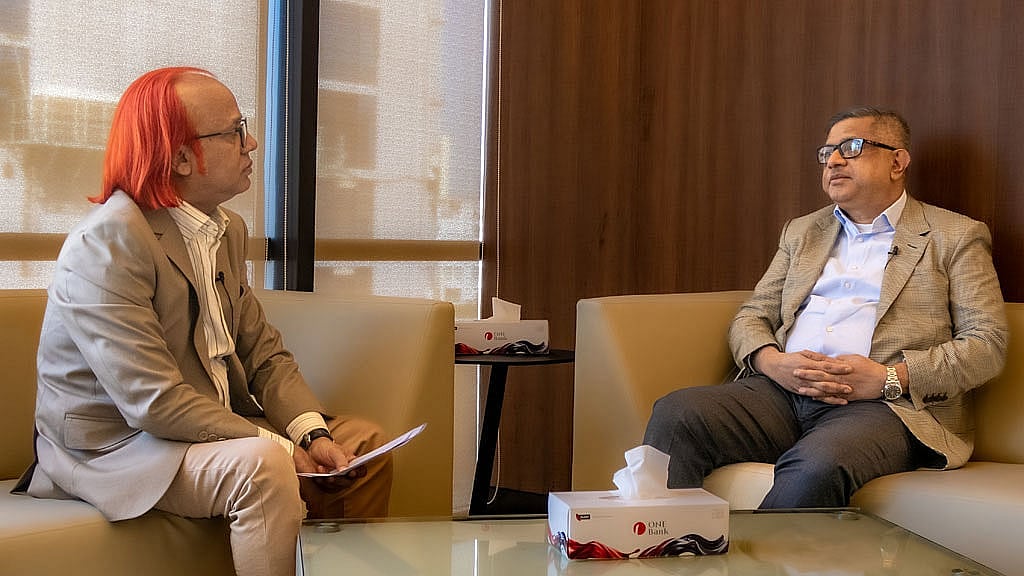
On bdnews24.com’s “Chinwag with the Chiefs”, Muhit discussed bad loans, pressure from influential borrowers, digital banking and ONE Bank’s plans. He proposed recovery task forces and early-warning systems to identify borrowers at risk before they default.
After more than 30 years at multinational banks, Muhit said he had brought a focus on governance, cash-flow-based lending and risk monitoring to ONE Bank.
“I see enormous scope for a local bank in these areas. By bringing my experience to the table, I believe I can play a special role in taking the bank to the next level in Bangladesh,” he said.
“Deposits have always depended on customer confidence. Trust is the key. Over the past 10 months, net deposits at ONE Bank have increased by Tk 50 billion, which is a major milestone for us.”
The bank has secured Bangladesh Securities and Exchange Commission approval to raise Tk 4 billion through a bond, with the process nearing completion. Muhit credited deposit growth to its established corporate base and improved digital services, including initiatives with Nagad.
The latest Bangladesh Bank figures put non-performing loans above Tk 6 trillion, nearly 36 percent of all loans disbursed by scheduled banks. The bad-loan burden has also weakened confidence in the sector.
Muhit said ONE Bank had formed a recovery task force, monitored by an internal team. It is exploring how closed or partly operational factories could restart with fresh loans or support under Bangladesh Bank schemes.
“Not all of them are non-performing loans. Many factories are closed for various reasons and are not getting the support they need,” he said.
For factories beyond recovery, the bank is considering auctions to find new buyers.
“If we can address all these issues together, we can gradually reduce non-performing loans while continuing to grow deposits and restore customer confidence. That is where we are focusing,” he said.
‘Responsibility Does not Lie with One Side’
Asked whether banking irregularities were the fault of Bangladesh Bank or commercial lenders, Muhit declined to blame either side alone. He said multinational banks had lower default rates because of stronger processes, monitoring and governance.
“First, you can alert a customer in advance not to expand further, or warn them that a particular area is becoming risky. That helps protect their business. You can also assess when you need to reduce or increase lending.”
Muhit said influential people could not force banks to approve loans if safeguards were strong.
He said such systems serve both sides: borrowers can be warned against risky expansion, while lenders can decide when to tighten or increase credit. Stronger oversight, he argued, would help prevent businesses from sliding into default and protect banks’ depositors as well.
“If we have processes, credit policies, support from the regulator and strong management capabilities, pressure cannot make it happen,” he said.
“A bank runs on customers’ deposits. Investing that money properly and recovering it is the responsibility of all stakeholders. I do not think there is room to do otherwise under pressure.”
He said banks must learn from the economic shock and move beyond an excessive focus on corporate lending.
Greater attention to small and medium-sized enterprises and retail customers would bring more people into formal finance.
“If everyone goes back to operating in the same way and focuses only on corporate banking, it will not work.”
Muhit sees considerable potential in digital banking. ONE Bank is investing in its ONE App and OK Wallet, whose growth had been held back by a lack of interoperability with other operators.
The introduction of Bangla QR now allows OK Wallet users to make payments across different wallets.
“This is a groundbreaking step. Transactions through OK Wallet have increased significantly,” he said, calling it an opportunity to bring unbanked people into the financial system.
ONE Bank’s 27-year history and corporate customer base are key strengths, Muhit said. It has 114 branches, more than 50 sub-branches and payment links to utility companies and government services, including tax, vehicle tax token and passport fees. It is digitising services that still involve manual work.
Despite fragile loan growth, he sees scope for recovery through development projects, exports beyond readymade garments, foreign investment and multilateral financing for small businesses.
“Ultimately, if we want economic growth across Bangladesh, we have to bring everyone into the banking system and banking channels,” he said.
Muhit aims to make ONE Bank one of the country’s leading lenders within five years, citing its multilateral funding in 2016-18 and deposit growth of more than Tk 50bn this year.
“There are huge opportunities for us in digital services and mobile financial services over the next five years. We can also grow in SMEs, mid-sized enterprises and retail banking,” he said.
“Human resources are extremely important, and I intend to make them a major focus. If we can do all these things, I hope ONE Bank will rise into the upper tier of the rankings within five years.”